Our Guide to the Top Military Credit Cards
There are plenty of credit cards on the market, which makes it easy to find the perfect one for you! Explore your options and connect with banks offering cards designed for cash back, travel, and other types of reward.

Credit card applications can be daunting, especially if it’s your first time.
Tons of card options exist, and they all have their own unique perks and costs. Choosing one can feel like a bit of a guessing game, since so many banks offer different cards—and each has its own set of requirements.
But don’t worry! This guide aims to simplify the process. It should help you find the card that’s right for you.
Types of Credit Cards
If you’re looking for an easy to read list, we’ve sorted credit cards by the features they offer. By comparing and exploring different options, you can find a card that fits your lifestyle.
Keep reading for a detailed understanding of credit cards, including deep dives into different card categories.
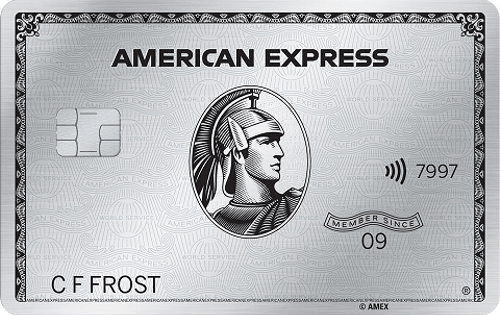
Our Top Choice: The Platinum Card® from American Express
American Express provides a substantial advantage to military personnel and their spouses by waiving annual fees on its credit cards, like The Platinum Card® and the American Express® Gold Card.
With annual fees of $695 and $250 respectively, this lesser-known benefit offers considerable cost savings for cardholders—especially service members attracted to the high-end perks of The Platinum Card® or the practical day-to-day benefits that the American Express® Gold Card offers.
Credit Cards: Why They’re Essential
In our digital age, financial tools like credit cards are key for flexible money management. Credit cards make everyday transactions a breeze—especially online shopping. Plus, some places like hotels and car rental agencies insist on a card for certain transactions.
While debit and prepaid cards might seem similar, they don’t offer the same protection as credit cards. One example is when it comes to unauthorized charges; credit cards often provide $0 liability, giving you a safety net against fraud. They also often include purchase protection, letting you dispute a purchase that didn’t live up to your expectations.
Besides, credit cards offer a ton of perks like attractive sign-up bonuses, ongoing rewards for spending, and collision damage waiver when you rent a car. For transactions made abroad, they also sometimes offer no fees on foreign transaction.
But the biggest perk? Credit cards can help strengthen your credit score. Unlike debit or prepaid cards, credit card payments are reported to the main credit bureaus: Equifax, Experian, and TransUnion.
It’s Best to Own Multiple Credit Cards
To take advantage of various benefits and build good banking relationships, it’s worth having a mix of credit cards. Managing three, or even four cards can set up multiple credit references, helping build a solid credit score and opening doors to better credit card offers.
It’s also a good idea to keep your existing credit cards—avoid canceling them. By keeping your cards active, you can extend your credit history which can elevate your credit score. Conversely, closing a credit card account reduces your active credit lines’ average age. This can dent your score.
Remember, though, credit cards are not all the same. So, while you’re aiming for at least three cards, make sure you’re picking cards that meet your needs and fit your lifestyle
Cards Favored by Experts in the Military Financial Community
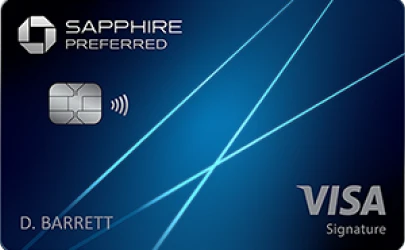
Chase Sapphire Reserve®
Receive 60,000 bonus points after you expend $4,000 on purchases within the first 3 months from account opening. That’s $900 toward travel when you redeem through Chase Ultimate Rewards®.
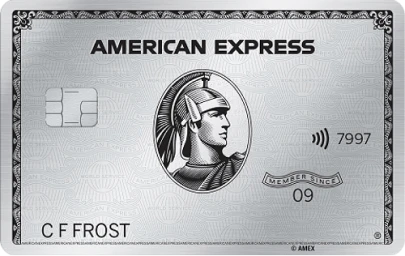
The Platinum Card® from American Express
Collect 80,000 Membership Rewards® Points after you spend $6,000 on purchases on the card within your first 6 months of card membership. Terms apply.
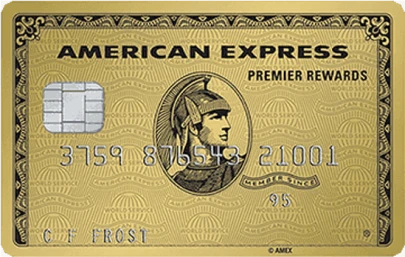
American Express® Gold Card
Accumulate 60,000 Membership Rewards® Points after you expend $4,000 on eligible purchases with your new card within the first 6 months of card membership. Terms apply.
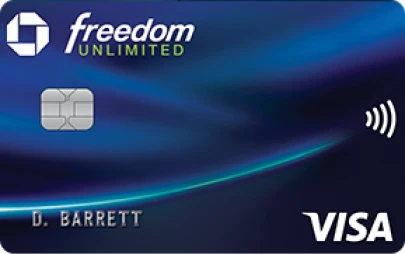
Chase Freedom Unlimited®
Earn an extra 1.5% on everything you buy (up to $20,000 spent in the first year)—worth up to $300 cash back. That’s 6.5% on travel purchased via Chase Ultimate Rewards®, 4.5% on dining and drugstores, and 3% on all other purchases.
Selecting the Best-Fit Credit Card
Your credit standing is a key factor when looking at credit card options. If you’ve got a great credit history, meaning a score higher than 700, you’ll have plenty of cards to choose from.
In fact, you might already be getting loads of offers from card issuers.
Pick a Card That Suits Your Lifestyle
Think about your spending habits and what you want in a card. Let’s say you travel a lot. Then, a travel rewards card could be a good fit. If travel isn’t your thing, a cash back rewards card might be better. If you’re a business owner, a business credit card is a must.
No matter your interests, there’s a credit card rewards program out there for you.
If you’re trying to get away from a high-interest credit card, a balance transfer card—ideally with a long 0% introductory period—could be worth considering.
If you’ve had credit problems before or you’re looking for a solid first card, explore credit builder cards (both secured or unsecured). And if you’re a student and have a limited credit history, start with a student credit card since they’re often designed for people with little credit. For another way to build your credit, you could become an authorized user on a trusted friend or family member’s credit card account.
Getting to Know Credit Cards
We’ve talked a lot about the perks of having a credit card, but let’s not forget the important details.
Repayments
Like any loan, you’ll face monthly repayments. Credit cards usually have a minimum repayment amount, usually about 2% to 3% of the balance. But remember, if you only make minimum payments, your balance will take longer to pay. Paying more each month lowers your balance faster and saves you interest.
Interest
Compared to other types of loads, credit cards usually have higher interest rates. Things like home or auto loans might have rates around 4% to 5%, whereas credit card interest rates typically range from 15% to 25% or more.
Grace period
Credit cards usually have a grace period where no interest is charged on purchases if you pay them off in a certain time, typically 25 to 30 days. But any balance left after that period will accrue interest.
Fees
Credit cards often come with a yearly fee, typically less than $100. Also, watch out for over-limit and late fees. Over-limit fees and late fees fees can be around $35 to $45 and can kick in if you’re even a single day late with a payment or go over your limit by just a dollar.
It’s a smart move to pay off your full balance every month. If your card has a 24% interest rate, you’ll pay 2% every month as interest. For example, on a $3,000 balance, that’s $60 in interest. Even with attractive rewards, the cost of interest can easily outweigh any benefits.
And finally, always be on the lookout for fraud. Identity theft and credit card theft are common, so check your account closely and frequently. If your card gets stolen, make sure to report it right away.
Guidelines on Identifying the Right Credit Card
Choosing the perfect credit card can be challenging—they have diverse terms, limits, qualification criteria, and benefits. It’s crucial to scrutinize these factors to determine which card best fits your needs.
Different types of credit card users will require different cards. Here are some key factors to consider.
Credit History
When your credit isn’t strong enough to qualify for your first choice of card, don’t panic: there are ways to improve it. This could involve settling overdue balances, reducing current credit card debt, or disputing erroneous negative information. Even a slight boost to your credit score can significantly affect the cards you qualify for.
Long-Term Benefits
While a card’s sign-up bonus or a tempting introductory offer might look appealing, don’t forget to also check the standard interest rate that comes with it. These short-term perks will eventually end, and you’ll be left with the regular interest rate. If a card comes with a higher rate than your existing one, the temporary benefits may not make the long-term costs worth it.
No-Fee vs. Annual Fee
Just because a card doesn’t charge an annual fee doesn’t necessarily mean it’s a superior deal. A card with a yearly fee might offer bigger and better rewards, which could make it more valuable than a no-fee card in the long run.
Application Process
Applying for multiple credit cards at the same time can harm your credit score. It’s wiser to do thorough research and limit your applications to a couple of cards (maximum) that best suit your needs.
With these factors in mind, we offer a comprehensive overview of various credit card options.
For detailed information about each card, check out our comprehensive reviews.
After reviewing the available options, connect with trusted banks that offer suitable credit card solutions for veterans.
Dive Into Different Credit Card Categories
There’s a wide variety of credit cards available, each designed to match different spending habits. For example, if you are able to consistently pay off your entire credit card balance every month, a rewards credit card may prove a more beneficial choice. Depending on the specific purchase, you might want to alternate between different cards; let’s say, a travel rewards card along with a cash back credit card. This way, you can choose the one that delivers the biggest rewards.
However, it’s crucial to remember that everyone’s spending habits differ, and you might find that another kind of credit card better suits your needs. For example, you might want a credit card with a balance transfer option; a student credit card; a card designed for small businesses; one with a low interest rate; one offering rewards in the form of hotel or airline perks, or another specialized card.
Below are categories that can steer you towards the perfect credit card tailored to your specific needs.
Introductory Offer Credit Cards
These featured credit cards with introductory offers present an opportunity to earn cash rewards starting from $100. All you need to do is open a new credit card—but remember, you’ll need to meet a minimum spending requirement, too.
Ideal for: Those intrigued by the prospect of maximizing credit card rewards.
Secured Credit Cards
Want to enhance your credit score—or perhaps you don’t have one at all? A secured credit card can assist you in this pursuit while offering all the typical benefits and protections. Got an average credit score? Then consider cards designed for those with fair credit.
Ideal for: Individuals aspiring to start their credit history journey or improve their credit score.
Cash Rebate Credit Cards
Favoured by many, cash back credit cards offer a simple and straightforward way to earn back a percentage of your spending. With a range of cash reward programs, these cards can help maximize returns on your everyday expenses.
Ideal for: Those seeking returns on daily expenditures like groceries, gas, dining out, travel, and more.
Student Credit Cards
These cards enable young individuals to establish their credit score and history early on. These cards also help students learn to use a credit card responsibly and earn coveted rewards like points and cash back.
Ideal for: Students and young individuals seeking to build their credit history.
Interest-Free Credit Cards
No-interest credit cards offer a 0% interest rate for balance transfers and/or purchases for a set period after the card is issued. They’re an excellent option for those looking to fast-track credit card debt repayment or take advantage of no-interest borrowing. Plus, a lot of these 0% APR cards feature appealing rewards programs.
Ideal for: Those wanting to expedite their credit card debt repayment or seeking borrowing options without interest.
Rewards-Based Credit Cards
Rewards cards come with a range of points, travel, and cash rewards, helping you maximize benefits from your regular spending. You can select the card with the optimal rewards structure which aligns with your needs.
Ideal for: Individuals seeking to optimize their everyday purchases.
Debt Consolidation Credit Cards
Struggling with credit card debt? Consider transferring your existing balance to a debt consolidation credit card with a 0% interest offer. This can be a smart way to dodge high-interest payments, potentially saving you significant money.
Ideal for: Those aiming to accelerate their journey towards financial freedom.
Business Credit Cards
Business credit cards can provide a wealth of benefits for any business owner. I regularly utilize mine for business-related expenses and appreciate the protections and opportunities to earn rewards like cash back.
Ideal for: Small business owners aiming to earn rewards on routine business expenses, grant credit card access to their employees, or streamline their finances.
Low Interest Rate Credit Cards
If you regularly maintain a balance on your credit card, a card with a low ongoing interest rate might be a smart choice. These credit cards offer competitive interest rates, potentially saving you money.
Ideal for: Individuals who typically maintain a balance on their credit cards.
Frequent Flyer Credit Cards
This type of card is ideal for regular air travellers loyal to a particular airline. Signing up can lead to attractive benefits like free airline tickets, cashback rewards, and the chance to earn free upgrades—plus other perks.
Ideal for: Regular air travellers who prefer a particular airline.
Fuel Rewards Credit Cards
If you drive frequently, these credit cards can offer significant savings on gas costs.
Ideal for: Drivers seeking to earn rewards (including cash) for their travel.
Travel Incentives Credit Cards
This type of card is perfect for travel enthusiasts, offering the opportunity to earn travel and cash benefits, including complimentary flights and hotel stays.
Ideal for: Frequent travellers or those wanting to maximize value from their rewards.
Even More Credit Card Deals
Interested in exploring a variety of credit card options? Our website provides valuable insights into credit cards, like exclusive deals, in-depth reviews of individual credit cards, comprehensive comparisons of credit card categories, options for individuals with poor credit, cards suitable for people with a fair credit score, plus many more enticing credit card offers.
Once you’ve identified a credit card that aligns with your needs, we can assist you in connecting with banks offering similar options. Our aim is to provide a platform for you to examine and compare various credit card options, helping you make a well-informed decision.
Join Our Mailing List
Enter your details below to join our mailing list and get weekly updates—for free!